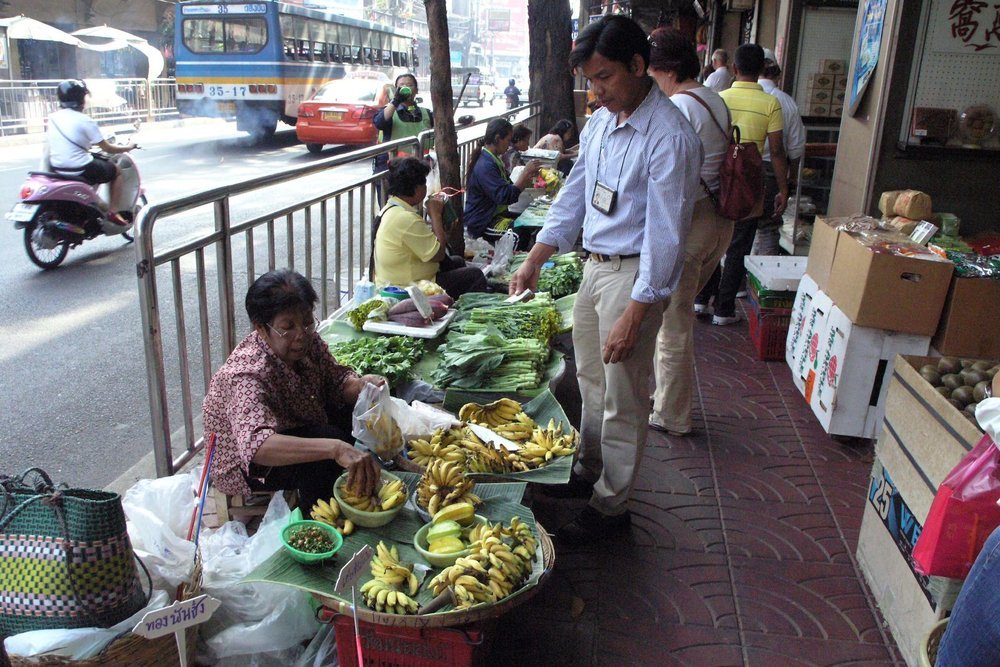
Small and medium-sized enterprises are the backbone of Thailand's economy. They account for a large share of businesses and employment, spanning everything from family shops and market stalls to manufacturers, restaurants and a growing cohort of technology startups. How easily these firms can obtain finance has a direct bearing on jobs and growth.
Access to credit is a long-standing hurdle. Smaller firms often struggle to borrow from banks because they lack the collateral, formal accounts or credit history that lenders typically require. Many operate wholly or partly in the informal economy, which makes it harder to prove income and assess risk. The result is that otherwise viable businesses can find it difficult to fund expansion, equipment or working capital.
This financing gap matters because small firms are usually the most sensitive to a shortage of cash. A profitable shop or workshop can still fail if it cannot bridge the timing between paying suppliers and being paid by customers — the classic cash-flow squeeze that affects small enterprises everywhere.
The picture has been changing, however, helped by the spread of digital finance. Thailand has a widely used national instant-payment system that lets individuals and businesses send and receive money cheaply using a phone, which has pulled more small transactions into the formal, recorded economy. That digital trail can, over time, make it easier for lenders and fintech firms to assess a small business and extend credit.
A growing fintech sector is building on those rails with digital lending, payment tools and other services aimed at smaller firms. Alongside this, government and state-linked institutions have long run schemes intended to support SME lending, guarantees and training, reflecting how important the sector is to the economy.
For the entrepreneurs themselves, the practical lessons are familiar but important: keeping clear records, formalising the business where possible, separating personal and business money, and understanding cash flow as distinct from profit. These steps not only improve day-to-day management but also make a firm more credible to a lender.
The broader story is one of a huge, vital sector gradually gaining better access to finance as digital payments and new lenders reduce the frictions that held it back — while the fundamentals of running a sound small business remain as important as ever.